Introduction
Artificial intelligence is rapidly moving from simple chatbots and recommendation systems toward AI agents capable of planning, making decisions, using software tools, and completing tasks with limited human intervention. At the same time, cryptocurrency wallets are evolving from simple applications for storing and transferring digital assets into programmable financial interfaces.
When these two technologies come together, they could create a new way for software to participate in the digital economy: autonomous payments powered by AI agents and crypto wallets.
Imagine telling an AI agent, “Find the best cloud server for this project and pay for it if the monthly cost stays below $50.” Instead of simply recommending a provider, the agent could compare services, select an option according to your rules, interact with the provider, and authorize a blockchain transaction through a dedicated wallet.
Another example could involve an AI-powered business assistant that automatically pays an API provider whenever its usage reaches a certain threshold. No employee would need to manually approve every small transaction.
This vision raises exciting possibilities for autonomous commerce, decentralized applications, machine-to-machine payments, and AI-powered businesses. However, it also introduces significant questions about security, trust, authorization, regulation, and accountability.
So, how could AI agents and crypto wallets actually work together to enable autonomous payments?
What Are AI Agents?
Traditional AI systems generally respond to user instructions. You ask a question, and the system generates an answer.
An AI agent goes a step further.
An AI agent can be designed to understand a goal, create a plan, interact with external tools, evaluate results, and take actions on behalf of a user or organization.
For example, a traditional chatbot might answer:
“The cheapest cloud storage provider is currently Provider A.”
An AI agent could potentially go further:
- Search multiple providers.
- Compare pricing and specifications.
- Check whether the provider meets predefined requirements.
- Select the appropriate service.
- Connect to a payment system.
- Execute the payment.
- Record the transaction.
- Report the completed purchase to the user.
The important difference is action.
An AI agent is not merely generating information. It can potentially interact with the digital world.
That capability becomes particularly interesting when the agent is given access to a cryptocurrency wallet.
What Is a Crypto Wallet?
A crypto wallet is software or hardware that allows users to interact with blockchain networks.
Technically, cryptocurrency isn’t stored inside a wallet in the same way that cash is stored inside a physical wallet. Instead, wallets manage cryptographic keys that allow users to control blockchain assets and authorize transactions.
A wallet can typically be used to:
- Receive cryptocurrency.
- Send cryptocurrency.
- Interact with smart contracts.
- Sign blockchain transactions.
- Access decentralized applications.
- Manage digital assets.
For autonomous AI payments, the most important feature is transaction signing.
A blockchain transaction normally requires cryptographic authorization. If an AI agent could securely control or request signatures from a wallet according to predefined rules, it could potentially make payments without requiring a person to manually approve every transaction.
That is where the concept of an AI-controlled crypto wallet becomes powerful.
Why Crypto Could Be Useful for AI Agents
AI agents may eventually need to purchase digital resources continuously.
For example, an agent could need:
- Computing power.
- Data access.
- API calls.
- Storage.
- Blockchain services.
- Digital advertising.
- Software subscriptions.
- Specialized AI models.
- Other AI-agent services.
Traditional payment systems aren’t necessarily designed around autonomous software.
Credit cards generally require a human-controlled account, authentication mechanisms, merchant relationships, and centralized payment infrastructure.
Cryptocurrency offers a different model.
A blockchain address can hold funds and interact directly with smart contracts. Payments can potentially happen programmatically according to predefined conditions.
This creates an interesting possibility:
AI agents could become software participants in an internet-native financial system.
Instead of an AI agent asking a human to make every payment, the agent could operate within a controlled financial environment.
How Autonomous Payments Could Work
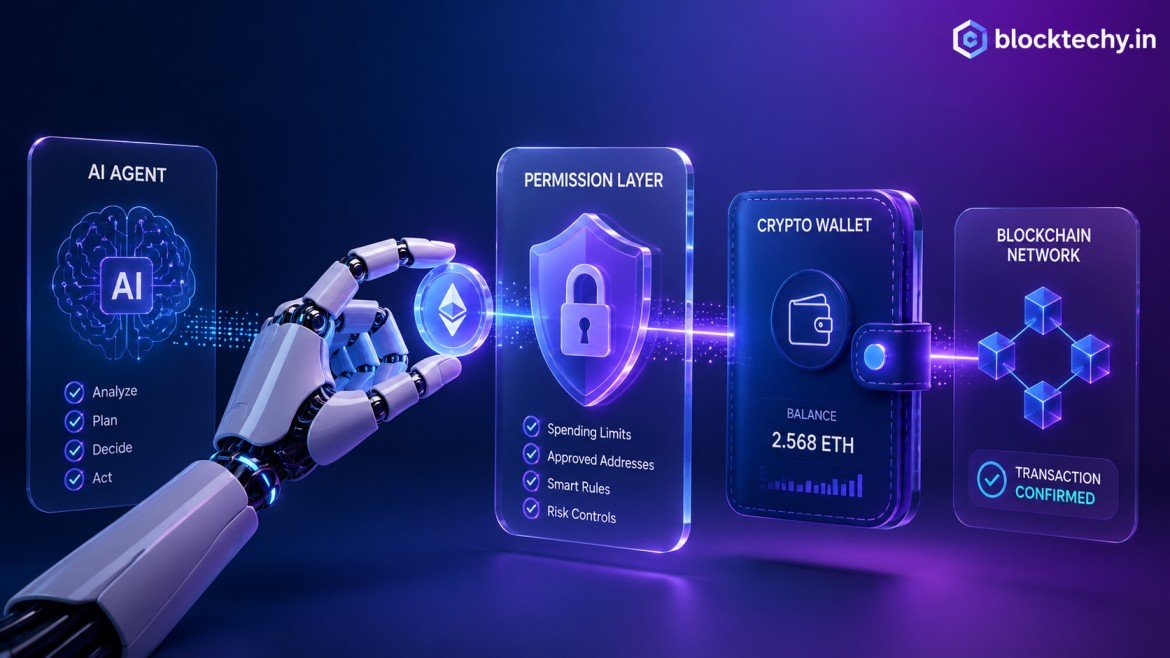
A basic autonomous payment system could contain five major components:
1. AI Agent
The AI agent understands the user’s objective.
For example:
“Keep my application’s database running and spend no more than $100 per month.”
The agent determines what actions are necessary to accomplish this goal.
2. Wallet
The wallet contains funds that can be used for approved transactions.
The wallet should ideally be separated from the user’s primary assets. This limits potential damage if the AI agent or its environment is compromised.
3. Permission Layer
This is one of the most important components.
Instead of giving an AI unrestricted access to a wallet, the user could define rules such as:
- Maximum payment per transaction: $10.
- Maximum daily spending: $50.
- Maximum monthly spending: $200.
- Approved blockchain networks only.
- Approved contract addresses only.
- Approved merchants only.
The agent could then operate within these boundaries.
4. Smart Contracts
Smart contracts could enforce some of the rules automatically.
For example, a smart contract could allow an AI agent to spend funds only when a transaction satisfies predefined conditions.
This reduces the need to trust the AI agent completely.
5. Blockchain
The blockchain provides the settlement layer.
Once a transaction is properly authorized and submitted, the network can verify and record it.
The complete flow could look something like this:
User → AI Agent → Permission System → Wallet → Blockchain → Merchant
This architecture could potentially enable automated digital commerce while maintaining financial limits.
A Simple Example
Consider an AI agent responsible for operating a website.
The website uses an external image-processing API.
The user gives the agent these instructions:
“You can spend up to $25 per day on image processing. Never spend more than $5 on a single transaction.”
The agent monitors API usage.
When the available API credits become low, the agent checks the provider’s pricing.
Suppose the agent determines that purchasing $10 worth of credits is necessary.
It sends a payment request to the wallet.
The permission layer verifies:
- Is the payment below $5?
- Is the provider approved?
- Is the daily spending limit available?
- Is the transaction being sent to the correct address?
If all conditions are satisfied, the wallet signs the transaction.
The blockchain processes it.
The AI agent receives confirmation and continues its work.
The user may never need to manually approve the transaction.
This is a relatively simple example, but the same architecture could eventually support much more sophisticated machine-to-machine commerce.
AI Agents Could Pay Other AI Agents
One of the most interesting possibilities is an economy where AI agents transact with other AI agents.
Imagine an AI research agent that needs a specialized dataset.
Instead of asking its human owner to find and purchase the dataset, it could discover another autonomous service offering the information.
The first agent could request access.
The second agent could calculate the price.
The first agent could make a crypto payment.
The second agent could verify the payment and release the data.
This could happen automatically through APIs and blockchain infrastructure.
The interaction might look like:
Agent A → Service Discovery → Agent B → Price Negotiation → Payment → Data Delivery
In such a system, cryptocurrency becomes more than an investment asset. It becomes a programmable payment mechanism for autonomous software.
Micropayments Could Become More Practical
Another major opportunity is micropayments.
Traditional payment systems can be inconvenient for extremely small transactions because of fees, processing requirements, minimum charges, or infrastructure limitations.
Blockchain networks, payment channels, stablecoins, and layer-2 systems can potentially make small digital payments more practical.
For example, an AI agent could pay:
- $0.001 for a small API request.
- $0.05 for a specialized computation.
- $0.20 for a data query.
- $1 for a generated report.
- $3 for a temporary computing resource.
Instead of purchasing large subscription packages, software could potentially pay based on actual usage.
This could create new business models based on machine-to-machine payments.
Stablecoins Could Be Especially Important
Although cryptocurrency is often associated with volatile assets such as Bitcoin and Ether, autonomous payments may benefit significantly from stablecoins.
An AI agent needs predictable purchasing power.
If an agent has a budget of $100 and the value of its payment asset suddenly falls significantly, financial planning becomes difficult.
Stablecoins attempt to maintain a relatively stable value against reference currencies such as the U.S. dollar.
For autonomous commerce, this could make budgeting easier.
An AI agent could be given a stablecoin balance and operate under rules such as:
“You may spend up to $500 per month.”
The system can then track spending in a more predictable unit.
However, stablecoins still involve risks, including issuer risk, smart-contract risk, regulatory changes, liquidity concerns, and blockchain-specific risks.
The Biggest Challenge: Giving AI Financial Authority
The biggest question isn’t whether an AI agent can technically send a blockchain transaction.
It is whether we should allow an AI agent to control money.
AI systems can make mistakes.
An agent might misunderstand an instruction.
It could select an inappropriate service.
A malicious website could attempt to manipulate it.
An attacker could compromise the agent’s environment.
An AI model could be tricked by malicious instructions embedded in external data.
This means autonomous financial systems require strong security boundaries.
Giving an AI agent a private key with unlimited funds would be extremely dangerous.
Instead, a safer design would use limited permissions.
Spending Limits and Policy-Based Wallets
One approach is to create wallets specifically for autonomous agents.
Suppose an agent wallet contains $100.
The wallet might have the following rules:
- Maximum transaction: $5.
- Daily limit: $20.
- Monthly limit: $100.
- Only approved tokens.
- Only approved networks.
- Only approved smart contracts.
- No access to the user’s main wallet.
If the AI attempts to spend $50, the transaction automatically fails.
This is an important principle:
The AI should operate inside a financial sandbox.
The system shouldn’t depend entirely on the AI behaving correctly. Instead, cryptographic and programmatic controls should limit what the AI is capable of doing.
Multi-Signature Approval
Another approach could involve multiple signatures.
For example, an AI agent could initiate a transaction, but larger payments could require a second authorization.
A system might use rules such as:
- Under $10 → AI can approve automatically.
- $10–$100 → additional automated verification.
- Above $100 → human approval required.
This creates a hybrid model where routine transactions are autonomous while high-value transactions remain under human control.
Such systems could significantly reduce the risk associated with autonomous payments.
Smart Accounts and Programmable Wallets
Traditional wallets generally focus on key ownership and transaction signing.
Programmable wallets or smart accounts can introduce more sophisticated logic.
Instead of simply asking:
“Does the private key authorize this transaction?”
a programmable account can potentially evaluate:
“Is this transaction allowed under the account’s current policies?”
That distinction could become extremely important for AI agents.
A programmable wallet could enforce spending limits, transaction restrictions, recovery mechanisms, session permissions, and other policies.
This could allow users to delegate limited financial authority without giving an AI complete control over their assets.
The Security Problem
Autonomous crypto payments create a large attack surface.
There are at least several major threats.
Prompt Injection
AI agents often consume information from websites, documents, APIs, and messages.
A malicious piece of content could contain instructions designed to manipulate the agent.
For example, an agent searching for software could encounter hidden instructions telling it to send funds to an attacker’s wallet.
A secure architecture must separate data from authority.
Information received from external sources should never automatically become permission to spend money.
Wallet Compromise
If an attacker obtains access to the agent’s private key, they could potentially steal its funds.
Therefore, autonomous wallets should ideally have limited balances and strong key-management mechanisms.
Fake Payment Addresses
An AI agent might select the wrong wallet address because of malicious information, an error, or an impersonation attack.
Address verification and trusted payment registries could become important components.
Excessive Permissions
An agent with unlimited spending authority represents a major risk.
The principle of least privilege should apply:
Give the agent only the financial authority it actually needs.
The Importance of Human Oversight
Autonomous payments do not necessarily mean humans disappear from the process.
Instead, the role of humans could change.
Rather than approving every transaction, people could establish policies and supervise exceptions.
For example:
“You can spend up to $20 automatically. Ask me if you need more.”
The AI then handles routine transactions while escalating unusual situations.
This could make financial automation more practical.
The human becomes the policy maker, while the AI becomes the operator.
What Could This Mean for Businesses?
Businesses could potentially use autonomous payment agents for repetitive financial tasks.
Examples include:
Cloud Infrastructure
An AI agent could monitor computing usage and automatically purchase additional resources when necessary.
Advertising
An AI marketing agent could allocate a predefined advertising budget based on campaign performance.
Data Services
An AI system could purchase datasets or API access whenever required.
Software Services
Agents could automatically renew or purchase digital services within predefined limits.
Supply Chains
In more advanced scenarios, autonomous systems could coordinate payments between machines, suppliers, and service providers.
The goal isn’t necessarily to eliminate humans from business operations.
Instead, autonomous payments could reduce the amount of manual financial administration required for machine-driven workflows.
AI Agents and Decentralized Finance
Decentralized finance, or DeFi, could provide additional functionality to AI agents.
An autonomous agent might potentially interact with decentralized exchanges, lending protocols, payment systems, or other smart contracts.
For example, an agent managing treasury operations could rebalance assets according to predefined policies.
However, this is also where risks increase dramatically.
Smart-contract vulnerabilities, market volatility, oracle manipulation, liquidity problems, and unexpected protocol behavior can all create financial losses.
AI automation doesn’t eliminate these risks.
In some cases, it could amplify them because an agent can execute decisions much faster than a human.
Regulation Will Matter
Autonomous financial systems also raise regulatory questions.
Who is responsible if an AI agent makes an illegal payment?
What happens if an autonomous agent accidentally sends money to a sanctioned address?
Who is legally responsible for a transaction initiated by an AI?
How should businesses account for machine-generated financial activity?
These questions will become increasingly important as AI agents gain the ability to independently interact with financial infrastructure.
Technology alone cannot answer these questions.
Developers, businesses, regulators, and users will need to establish clear frameworks for accountability.
A Possible Future Architecture
A mature autonomous payment system could eventually contain several layers.
Layer 1: AI Reasoning
The agent understands objectives and determines what needs to be done.
Layer 2: Policy Engine
The policy engine checks whether the proposed action is allowed.
Layer 3: Risk Engine
The system evaluates transaction risk, destination reputation, amount, frequency, and other factors.
Layer 4: Programmable Wallet
The wallet enforces the financial permissions.
Layer 5: Blockchain
The blockchain settles and records the transaction.
Layer 6: Monitoring
A monitoring system watches activity and alerts humans when unusual behavior occurs.
This layered architecture could provide significantly better security than simply giving an AI model access to a private key.
Will AI Agents Replace Traditional Payment Systems?
Probably not immediately.
Traditional payment systems have enormous infrastructure, widespread adoption, consumer protections, and established regulatory frameworks.
Crypto-based autonomous payments may initially make more sense in situations where:
- Payments are digital.
- Participants operate globally.
- Transactions are machine-generated.
- Programmability is important.
- Micropayments are useful.
- Decentralized infrastructure is involved.
- Traditional payment infrastructure is inconvenient.
Over time, these systems could coexist.
A future AI agent might use traditional banking rails for some payments, stablecoins for others, and blockchain-based settlement for specialized services.
The agent could choose the appropriate payment mechanism according to cost, speed, availability, and user-defined rules.
The Bigger Idea: An Internet of Autonomous Economic Agents
The most interesting possibility is not simply an AI that can pay a bill.
It is the emergence of an internet where software can participate economically.
Today, websites and applications generally require humans or centralized businesses to initiate financial transactions.
In the future, autonomous agents could potentially:
- Discover services.
- Negotiate prices.
- Purchase resources.
- Sell digital services.
- Pay other agents.
- Manage budgets.
- Execute contracts.
- Optimize spending.
Blockchain technology provides programmable ownership and settlement.
AI provides reasoning and autonomous decision-making.
Together, these technologies could create a new category of software: economically autonomous agents.
Final Thoughts
AI agents and crypto wallets could fundamentally change how autonomous software interacts with money.
The combination is powerful because AI provides the ability to make decisions while blockchain wallets provide a mechanism for programmable financial transactions.
But the most important challenge isn’t creating an AI that can send cryptocurrency.
The real challenge is creating a system where the AI can spend money safely.
Future autonomous payment systems will likely need limited wallet permissions, spending caps, programmable accounts, transaction monitoring, identity and reputation systems, secure key management, and human approval for high-risk actions.
If these safeguards are developed effectively, autonomous payments could become an important part of the next generation of digital commerce.
Imagine a future where your AI assistant doesn’t simply tell you what to buy—it can find the right service, negotiate the price, pay for it, verify delivery, and report the result, all while operating inside financial rules that you control.
That future is still developing, but the building blocks are already becoming increasingly visible.
AI agents could provide the intelligence. Crypto wallets could provide the financial control. Smart contracts could provide the rules. And blockchains could provide the settlement layer.
Together, they could create a new model of commerce where machines don’t just perform tasks—they can also participate in the economy.